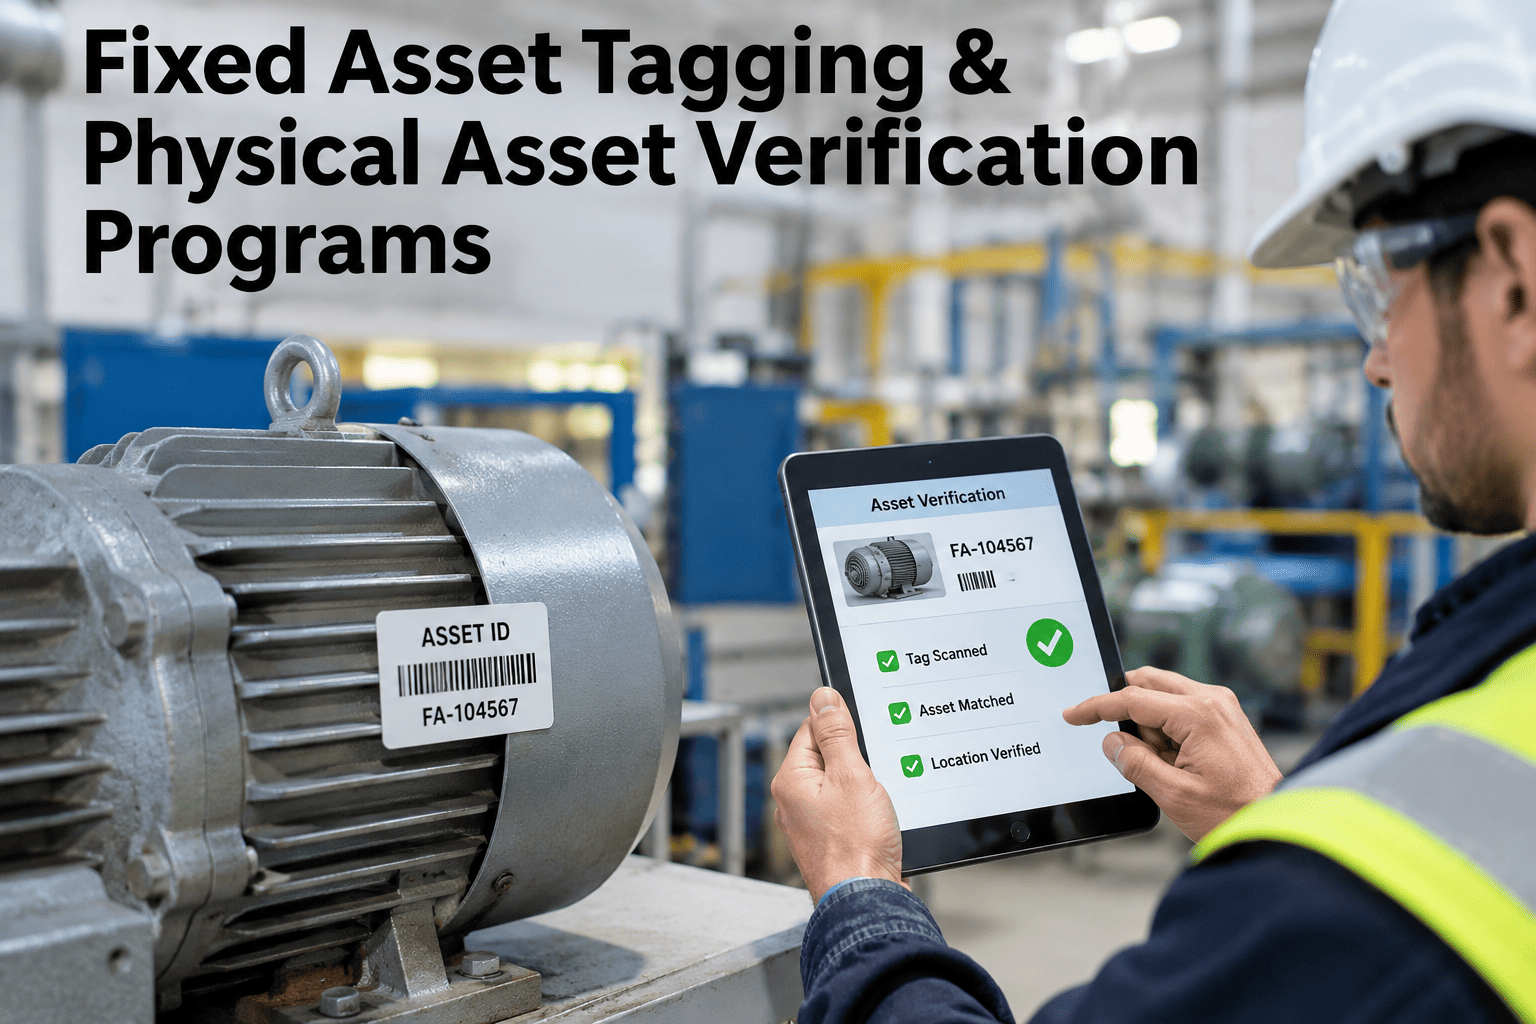
Most finance teams find out their asset register is wrong the hard way, usually when an auditor, an insurer, or a tax assessor asks a question nobody can answer with confidence. Fixed asset tagging is the practice of attaching a unique, scannable identifier to every physical asset and linking it to a single ledger record, while physical asset verification is the periodic walk-the-floor process that confirms the ledger still matches reality. Industry benchmark data from Sage Fixed Assets, AICPA, and EY puts the share of unreconciled fixed-asset ledgers made up of ghost assets — items still on the books that are missing, scrapped, or sold — at 10 to 30 percent of line items (Sage Fixed Assets / AICPA, 2026). iFactory, an on-premise AI platform with asset management and EAM capability built in, gives plant and finance teams a tagging and verification workflow that closes that gap before the next audit. Teams ready to see what their own register's ghost-asset exposure looks like can walk through a register reconciliation approach with our team.
Fixed Asset Tagging & Verification · 2026 Benchmark
Up to 30 Percent of an Un-Audited Asset Register Can Be Ghost Assets
iFactory AI pairs unique asset tags with a physical verification workflow, so the general ledger and the plant floor describe the same assets — and only the assets that are actually there.
0%Typical ghost-asset range: 10–30%100%
What a ghost asset is
A Ghost Asset Is a Record Without a Matching Physical Item
A ghost asset (OEE and asset-management terminology aside, this is a finance term) is any line in the fixed asset register that no longer corresponds to a real, locatable item. CPCON's 2026 audit methodology research groups most ghost assets into a few recurring causes, and knowing the cause determines the fix.
Disposed, not recorded
Scrapped or sold assets that were never removed from the ledger — the single most common type (CPCON, 2026).
Lost or stolen
Items that left the site without a disposal transaction ever being logged.
Relocated untracked
Equipment moved between departments, lines, or sites without updating its register location.
Duplicated on re-tag
A replacement tag issued without retiring the original record, so one asset exists twice.
What it costs
Ghost Assets Are Not a Paperwork Problem, They Are a Cash Problem
Every ghost asset keeps generating depreciation and keeps inflating the base used for property tax and insurance premiums, year after year, until someone finds it.
Overpaid tax
Property tax is often assessed against the book value of listed assets, ghosts included.
Inflated premiums
Insurers price coverage off the same inflated asset base.
Phantom maintenance
Maintenance budgets can carry PM schedules for equipment that is no longer there.
Audit exposure
Unexplained register-to-floor variance is a recurring finding in external and SOX-style audits.
Grand View Research puts the global fixed asset management software market at roughly $3.6 billion in 2024, growing to $6.9 billion by 2030 at an 11.4 percent CAGR (Grand View Research, 2026) — a signal that more finance teams are funding the cleanup rather than absorbing the loss every year.
Tagging standards
What Belongs on a Fixed Asset Tag
A tag only works if it is unique, durable, and machine-readable from a normal working distance. The table below is the minimum field set used in most physical verification programs.
| Field | Why it is captured | Typical format |
|---|
| Unique asset ID | One-to-one match to a single ledger line, never reused | Barcode or QR, sequential |
| Asset class/category | Groups similar items for depreciation and reporting | Short code |
| Acquisition date | Anchors the depreciation schedule | Date field |
| Assigned location | Detects unauthorized moves between verification cycles | Site/line/zone code |
| Custodian/department | Assigns accountability for condition and location | Cost center |
| Tag material | Must survive the asset's environment | Metal foil, polyester, anodized |
See Your Register-to-Floor Gap Before an Auditor Does
Share a sample of your current fixed asset register and iFactory AI will walk through what a structured tagging and verification rollout would look like for your asset count.
The verification cycle
Five Steps From Tagging to a Clean Reconciliation
1
Baseline the register
Export the current fixed asset ledger as the starting point for comparison.
2
Tag every located asset
Apply a unique, durable tag and scan it against the register line it matches.
3
Flag the unmatched
Register lines with no physical match become candidates for ghost-asset write-off.
4
Reconcile with finance
Finance reviews flagged lines and approves retirements, transfers, or corrections.
5
Set a recurring cadence
A register that is not re-verified drifts again — most programs run an annual or semi-annual cycle.
Spreadsheet vs platform
Why Spreadsheet-Based Registers Drift Fastest
Spreadsheet register
No link between a row and a physical tag
Manual updates are easy to skip
No audit trail for who changed what
Verification is a once-a-year scramble
iFactory AI asset register
Every asset tag is linked to one ledger record
Scans update location and status automatically
Full change history per asset
Verification runs as a continuous, scheduled process
Expert review
What an Asset Accountant Checks First
A tagging project succeeds or fails on discipline, not technology. The tag only has value if every asset movement, disposal, and acquisition updates the same record it is linked to.
Verdict
Strong when tagging and reconciliation are run as one engagement, not two separate projects.
Watch for
A register that is cleaned once and never re-verified — ghost assets reappear within a year or two.
Do next
Pilot tagging on one high-value asset category and reconcile it against the ledger within 30 days.
Frequently asked questions
What Finance and Plant Teams Ask About Asset Tagging
What percentage of a typical fixed asset register is ghost assets?
Industry benchmark data from Sage Fixed Assets and AICPA places the figure at 10 to 30 percent of line items in registers that have gone three or more years without a physical reconciliation (Sage Fixed Assets / AICPA, 2026).
See how this applies to your asset count.
How often should a physical asset verification be run?
Do we need to re-tag every asset we already have barcodes on?
What happens to assets we tag but cannot match to the register?
Can asset tagging reduce our property tax and insurance costs directly?
Removing confirmed ghost assets from the register lowers the book value used in many property tax and premium calculations, though the exact effect depends on your jurisdiction and policy terms.
Discuss your specific tax and insurance exposure.
Close the gap before the next audit
Give Your Asset Register a Single Source of Truth
Book a session with iFactory AI to design a tagging standard and verification cadence that fits your asset count and audit calendar.
{"@context":"https://schema.org","@type":"FAQPage","mainEntity":[
{"@type":"Question","name":"What percentage of a typical fixed asset register is ghost assets?","acceptedAnswer":{"@type":"Answer","text":"Industry benchmark data from Sage Fixed Assets and AICPA places the figure at 10 to 30 percent of line items in registers that have gone three or more years without a physical reconciliation."}},
{"@type":"Question","name":"How often should a physical asset verification be run?","acceptedAnswer":{"@type":"Answer","text":"Most programs run a full verification annually, with high-value or high-mobility asset categories checked more often."}},
{"@type":"Question","name":"Do we need to re-tag every asset we already have barcodes on?","acceptedAnswer":{"@type":"Answer","text":"Only if the existing tags are not uniquely linked to a single, current ledger record."}},
{"@type":"Question","name":"What happens to assets we tag but cannot match to the register?","acceptedAnswer":{"@type":"Answer","text":"They are logged as untagged finds, reviewed by finance, and either added to the register as new assets or investigated as transfers from another site."}},
{"@type":"Question","name":"Can asset tagging reduce our property tax and insurance costs directly?","acceptedAnswer":{"@type":"Answer","text":"Removing confirmed ghost assets from the register lowers the book value used in many property tax and premium calculations, though the exact effect depends on jurisdiction and policy terms."}}
]}