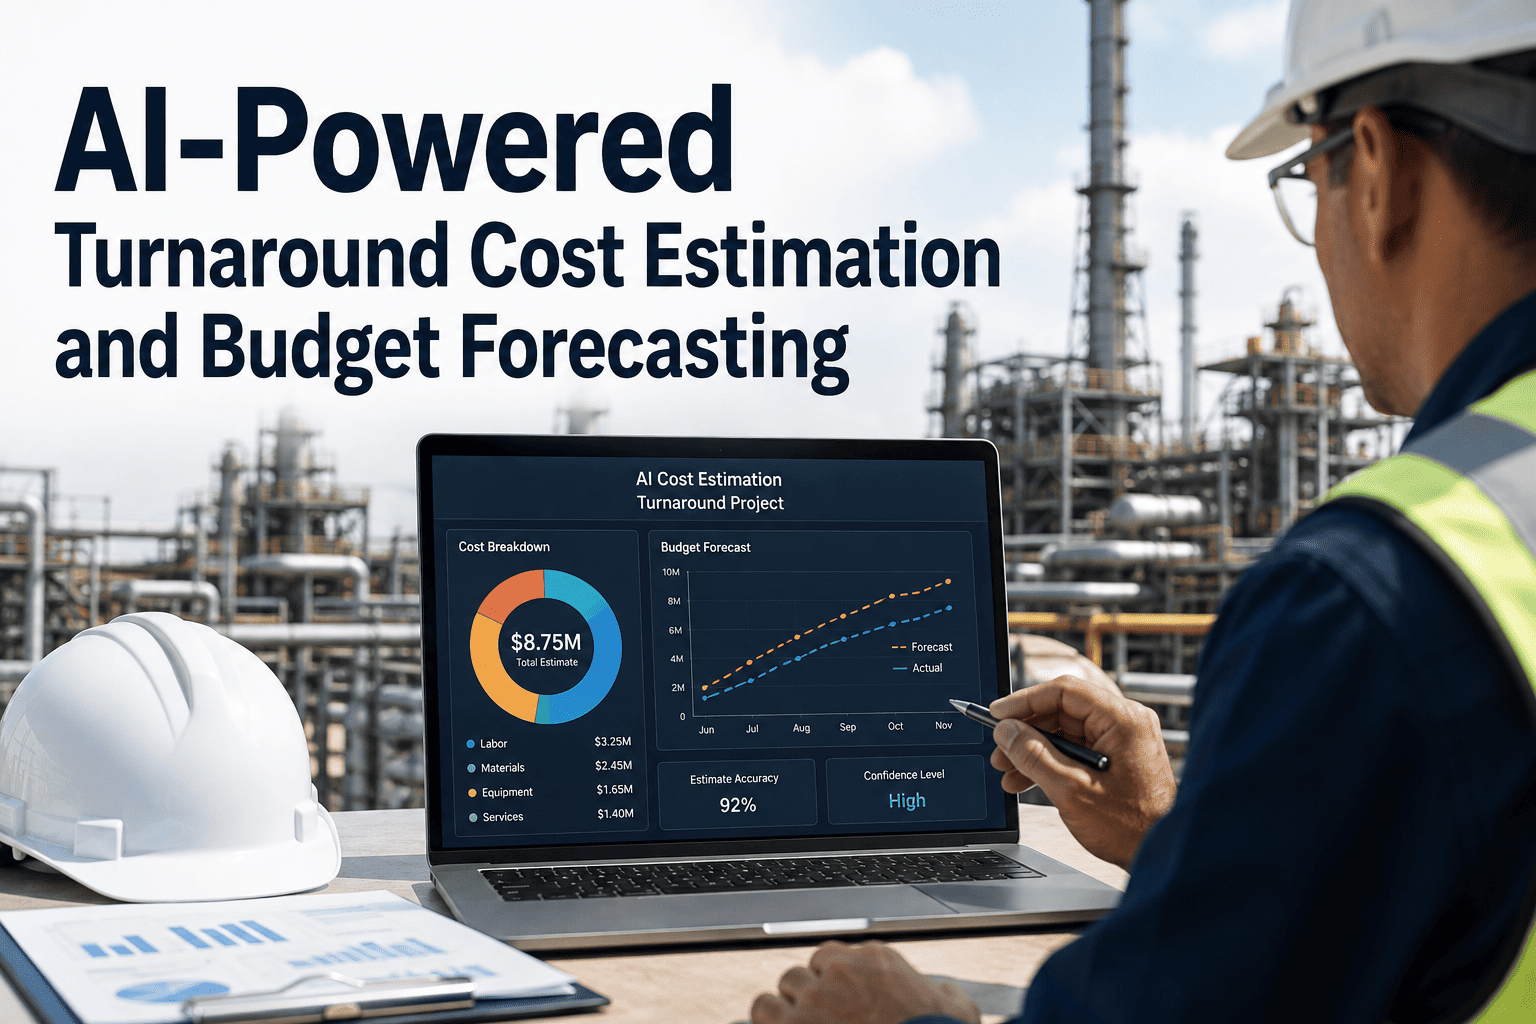
A turnaround budget is approved twelve to eighteen months before a single tool touches the unit, built on cost estimates for work that has not been fully scoped yet, executed by contractors whose final headcount is not locked until weeks before shutdown, and then measured against actual spend in an environment where emergent findings are all but guaranteed. It is one of the hardest cost control problems in industrial operations, and treating it like a normal capital budget — set once, tracked against a single number, reconciled at the end — is exactly why so many turnarounds close 15 to 30 percent over their original estimate. A benchmarked, tiered, and continuously tracked cost control process is what keeps that number closer to single digits. Our turnaround cost control specialists can review how your current estimate and tracking process compares to industry benchmarks.
Where Turnaround Budgets Actually Go, and Where They Actually Slip
Why Turnaround Costs Are Notoriously Hard to Control
A normal capital project budget is built around a fixed, engineered scope with a design that is largely locked before construction begins. A turnaround budget is built around a worklist that is still being challenged and refined for months after the initial estimate, executed by a temporary workforce whose availability and rates shift with the regional labor market, and always carries the near-certainty that some portion of the equipment being opened up will reveal a finding nobody could estimate in advance. This combination — moving scope, moving labor market, and guaranteed emergent findings — is what makes turnaround cost control fundamentally different from standard project cost management.
The organizations that control turnaround cost well do not do so by eliminating this uncertainty, because it cannot be eliminated. They do it by benchmarking the estimate against real industry data rather than internal guesswork, by sizing contingency reserves against actual risk tiers rather than a flat percentage applied out of habit, and by tracking earned value continuously through execution so that a cost trend is visible weeks before it becomes an overrun on the final invoice.
The Five Cost Categories That Make Up a Turnaround Budget
Understanding where turnaround money actually goes is the first step toward controlling it, because each category carries a different risk profile and a different control lever. Treating the whole budget as a single number to track against makes it impossible to tell whether an overrun is coming from a labor rate issue, a materials procurement issue, or simply more emergent scope than the contingency reserve was sized for.
Benchmarking Your Turnaround Cost Against Industry Data
An estimate built entirely from internal historical data can miss a shift in the broader market — a regional labor shortage driving up contract rates, or a materials category experiencing a supply constraint that did not exist during the last turnaround cycle. Benchmarking against industry-normalized cost-per-unit data catches these shifts before they show up as a surprise in the final estimate.
| Facility Type | Common Benchmark Metric | Typical Range |
|---|---|---|
| Refinery unit turnaround | Cost per barrel of daily throughput capacity | Industry-published ranges vary by unit complexity |
| Gas processing plant | Cost per MMSCFD of processing capacity | Varies with plant age and equipment count |
| Petrochemical unit | Cost per ton of annual production capacity | Highly dependent on catalyst and reactor scope |
| Cross-facility comparison | Cost per direct work-hour executed | Most consistent metric across facility types |
Cost per direct work-hour tends to be the most portable benchmark across different facility types and scopes, since it strips out the variability introduced by differences in unit size or production capacity and focuses purely on labor efficiency. Facility-specific metrics like cost per barrel or cost per ton are still valuable for year-over-year internal trending, but they are less useful for comparing performance against a different type of facility or a different region's labor market. A mature cost benchmarking program typically tracks both — an internal trend metric for continuity and an external metric for market comparison.
Sizing Contingency by Risk Tier, Not by Habit
The most common contingency mistake is applying a flat percentage — often 10 percent, simply because that is what the last few turnarounds used — without actually evaluating whether the current scope carries more or less risk than those prior events did. A turnaround with a well-inspected, recently-replaced vessel carries a very different emergent-finding risk than one going into a piece of equipment that has not been internally inspected in over a decade.
Tiering contingency this way also makes the reserve more defensible during budget approval, since leadership can see the specific risk basis behind the percentage requested rather than a flat number that looks arbitrary. It also improves control during execution, because a high-risk work front consuming its contingency reserve faster than expected is a specific, trackable signal rather than an ambiguous draw against one undifferentiated pool that could be masking a problem anywhere in the scope.
Tracking Earned Value Through Execution
The single biggest gap in turnaround cost control is not the estimate — it is the absence of a live tracking mechanism during execution that compares planned value against actual cost and actual progress on a rolling basis. Facilities that only reconcile cost at the end of the turnaround are, by definition, finding out about overruns after it is too late to correct them.
The pattern shown above is a common one — cost tracking on plan through the early weeks, a drift upward as emergent findings and schedule pressure accumulate in the middle of the turnaround, and a partial recovery in the final weeks as the control team applies corrective action once the trend becomes visible. That recovery only happens because the trend was visible early enough to act on. Without weekly earned value tracking, the same drift would only be discovered in the final reconciliation, well past the point where any corrective action could change the outcome.
Common Cost Overrun Drivers and Their Control Levers
Most turnaround cost overruns trace back to a small set of recurring drivers, each of which has a specific, known control lever available if the tracking process is in place to catch it early enough to apply that lever.
| Overrun Driver | Warning Signal | Control Lever |
|---|---|---|
| Emergent scope beyond contingency | Contingency draw rate exceeding the planned burn curve | Tiered risk reserve with a formal draw-down approval process |
| Labor productivity below plan | Work-hours consumed exceeding percent-complete progress | Daily crew productivity tracking against the resourced schedule |
| Materials cost escalation | Actual procurement cost exceeding the class 3 estimate | Locked pricing on long-lead items during the detailed planning phase |
| Schedule extension driving equipment rental | Critical path slippage against the baseline schedule | Weekly critical path and cost tracking tied to the same reporting cycle |
What Disciplined Cost Control Actually Delivers
Facilities that adopt benchmarked estimating, tiered contingency, and weekly earned value tracking consistently report tighter cost performance across turnaround cycles, independent of scope or facility type.
Building a Weekly Cost Control Governance Cadence
Tracking data weekly only produces value if there is a governance structure attached to it that actually acts on what the data shows. Facilities that generate weekly earned value reports but never build a decision-making cadence around them end up with excellent visibility into a problem they still cannot correct in time, because nobody with the authority to reallocate budget or crew is actually reviewing the numbers on the same weekly cycle they are produced.
| Cadence | Participants | Decision Authority |
|---|---|---|
| Daily cost flash report | Cost engineer, work front supervisors | Flag category-level variance for review, no spending authority |
| Weekly cost control meeting | Turnaround manager, cost engineer, discipline leads | Approve contingency draw-downs within tier limits |
| Bi-weekly leadership review | Site leadership, turnaround manager | Approve reserve reallocation across categories or tiers |
The daily flash report is intentionally lightweight — its purpose is early flagging, not decision-making, and giving it decision authority tends to either slow it down with debate that belongs in the weekly meeting or push urgent-sounding but low-priority items past people who should be focused on execution. The weekly cost control meeting is where the actual contingency draw-down decisions happen, using the risk-tier framework described earlier to keep those decisions consistent rather than ad hoc. The bi-weekly leadership review exists specifically for the reallocation decisions that cross tier or category boundaries, which are less frequent but carry more consequence, and which benefit from a slightly slower, more deliberate review cycle than the operational weekly meeting allows.